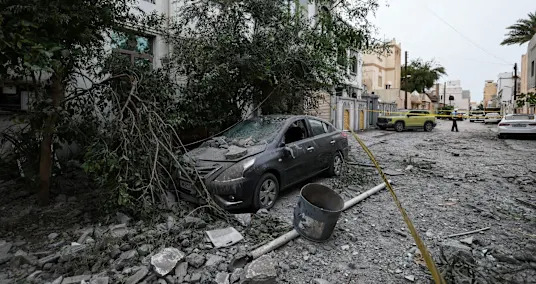

From petrol prices to mortgage rates, the US-Israel war with Iran has already had an impact on people's finances in the UK.
How deep and sustained that turns out to be depends on the duration of the conflict and how quickly supply lines and economies can recover.
Here are some of the areas to watch out for.
Fuel prices for motorists
Drivers may have already noticed that prices at the pump are on the rise.
By Friday, average petrol prices hit 150.11p a litre, up by 17.3p since the start of the conflict, while diesel had increased by 35.3p to 177.68p, the RAC motoring organisation said.
Earlier this month, the increase in pump prices triggered a row between petrol retailers and the government. Retailers accused the government of using "inflammatory language" by suggesting firms were profiteering from the oil price surge.
According to analysts, every $10 increase in oil pushes up pump prices by roughly 7p a litre.
Crude prices have risen sharply since the start of the war, although they are volatile as they react to the status of the conflict and commentary from the White House.
While motoring organisations say that there are plenty of supplies, they are encouraging people to reduce non-essential journeys. They also suggest people amend their driving style, by not accelerating or braking too hard to conserve fuel.
Not everyone has a car or may not use one for a daily commute. However, when petrol rises, it can carry through to higher prices for goods and services.
For example, if transport costs for supermarkets increase that could then be reflected in the cost of food.
Cost and choice of mortgages
Before the war began, there had been a hope and expectation of a steady fall in the interest rates charged on new, fixed mortgages, as well as lower variable rates.
Now, the opposite is happening.
Lenders have raised rates quickly, owing to their own funding costs rising and an expectation that the base borrowing rate will not fall as previously anticipated.
The average two-year fixed rate has jumped from 4.83% at the start of March to 5.75% now, its highest since last March, according to the financial information service Moneyfacts. The cheapest deals have risen the fastest.
For those looking for a five-year deal, the average rate has gone up from 4.95% to 5.69% over the same period and is now at its highest level since July 2024.
At times of economic uncertainty, lenders pull mortgage products off the shelves, reducing choice.
There are now 1,620 fewer residential mortgage products on the market, according to Moneyfacts, although that still leaves more than 6,000 deals to choose from.
LATEST POSTS
- 1
 New materials, old physics – the science behind how your winter jacket keeps you warm
- 2Plane Passenger Allegedly Includes ‘Bomb Threat’ in Hotspot Network Name, Forces Flight to Make Emergency Landing
- 3This widow influencer is using jokes to cope after her husband's death. It's OK if people don't get it.
- 4Share your pick for the riding area that characterizes your surf undertakings!
- 575% of US adults may meet criteria for obesity under new definition, study finds


- The Most Vital Crossroads in Olympic History
- Artemis 2 moon rocket gets 'America 250' paint job | Space photo of the day for Dec. 23, 2025
- Bahrain cracks down on dissent as war grinds on
- Netanyahu leads meeting on West Bank riots, Katz defends axing administrative detention for Jews
- Volkswagen Just Revealed a Massive Range-Extended SUV for China, and America Isn’t Getting It
- Watch the Geminid meteor shower peak tonight from the comfort of home with this free livestream
- Surveys of Thrillers That Re-imagined the Class
- A Colombian city swaps iconic horse buggies for electric carriages amid animal welfare concerns
- Fundamental Home Items Each Animal person Needs